

I was reading about the SEC comment letter to Cleanspark, Inc. here:

I decided to suggest another point of view on using the daily closing price instead of the daily lowest price when determining impairment expense for crypto assets.
When the daily lowest price falls below the current book value of a token, impairment testing of digital assets is triggered. However, the metric that could serve as a trigger indicator of potential impairment does not, by default, represent the fair value used to calculate impairment expense under FASB. ASC 350-30-35-19 requires comparing an indefinite-lived intangible asset's carrying amount with its fair value. If the carrying amount exceeds fair value, the excess is recognized as an impairment loss, and the resulting carrying amount becomes the asset's new accounting basis. [FASB ASC 350-30-35-19]
However, the daily lowest price would not constitute the fair value of the asset at the measurement date. Therefore, the daily lowest price should not be used to calculate crypto asset impairment charges. Why?
ASC 820 measures fair value based on the exit price in an orderly transaction between market participants at the measurement date. The measurement reflects current market conditions in the principal, or in its absence, the most advantageous, market and may be based on an observable price or another valuation technique. [FASB ASC 820-10-20; ASC 820-10-35-9A]
We cannot use the daily lowest prices to calculate the impairment charge, as it's unlikely to coincide with the fair value at the measurement date required under ASC 820. Simply put, the standards require measuring the fair value of intangible assets on a full-day basis, regardless of intraday fluctuations. Finally, daily lowest prices (by their nature) often reflect outlier transactions, not representative of an orderly transaction's executable price. The same idea appears in the answer to Question 6 in the AICPA’s Guide1.
In a fragmented2 crypto asset market, determining the principal market's daily low price requires a continuous process. This can lead to complicated and ambiguous outcomes that may not reflect a fair value compliant with FASB ASC 820 requirements.
As such, we believe that the following approach to the crypto asset impairment calculations may be appropriate:
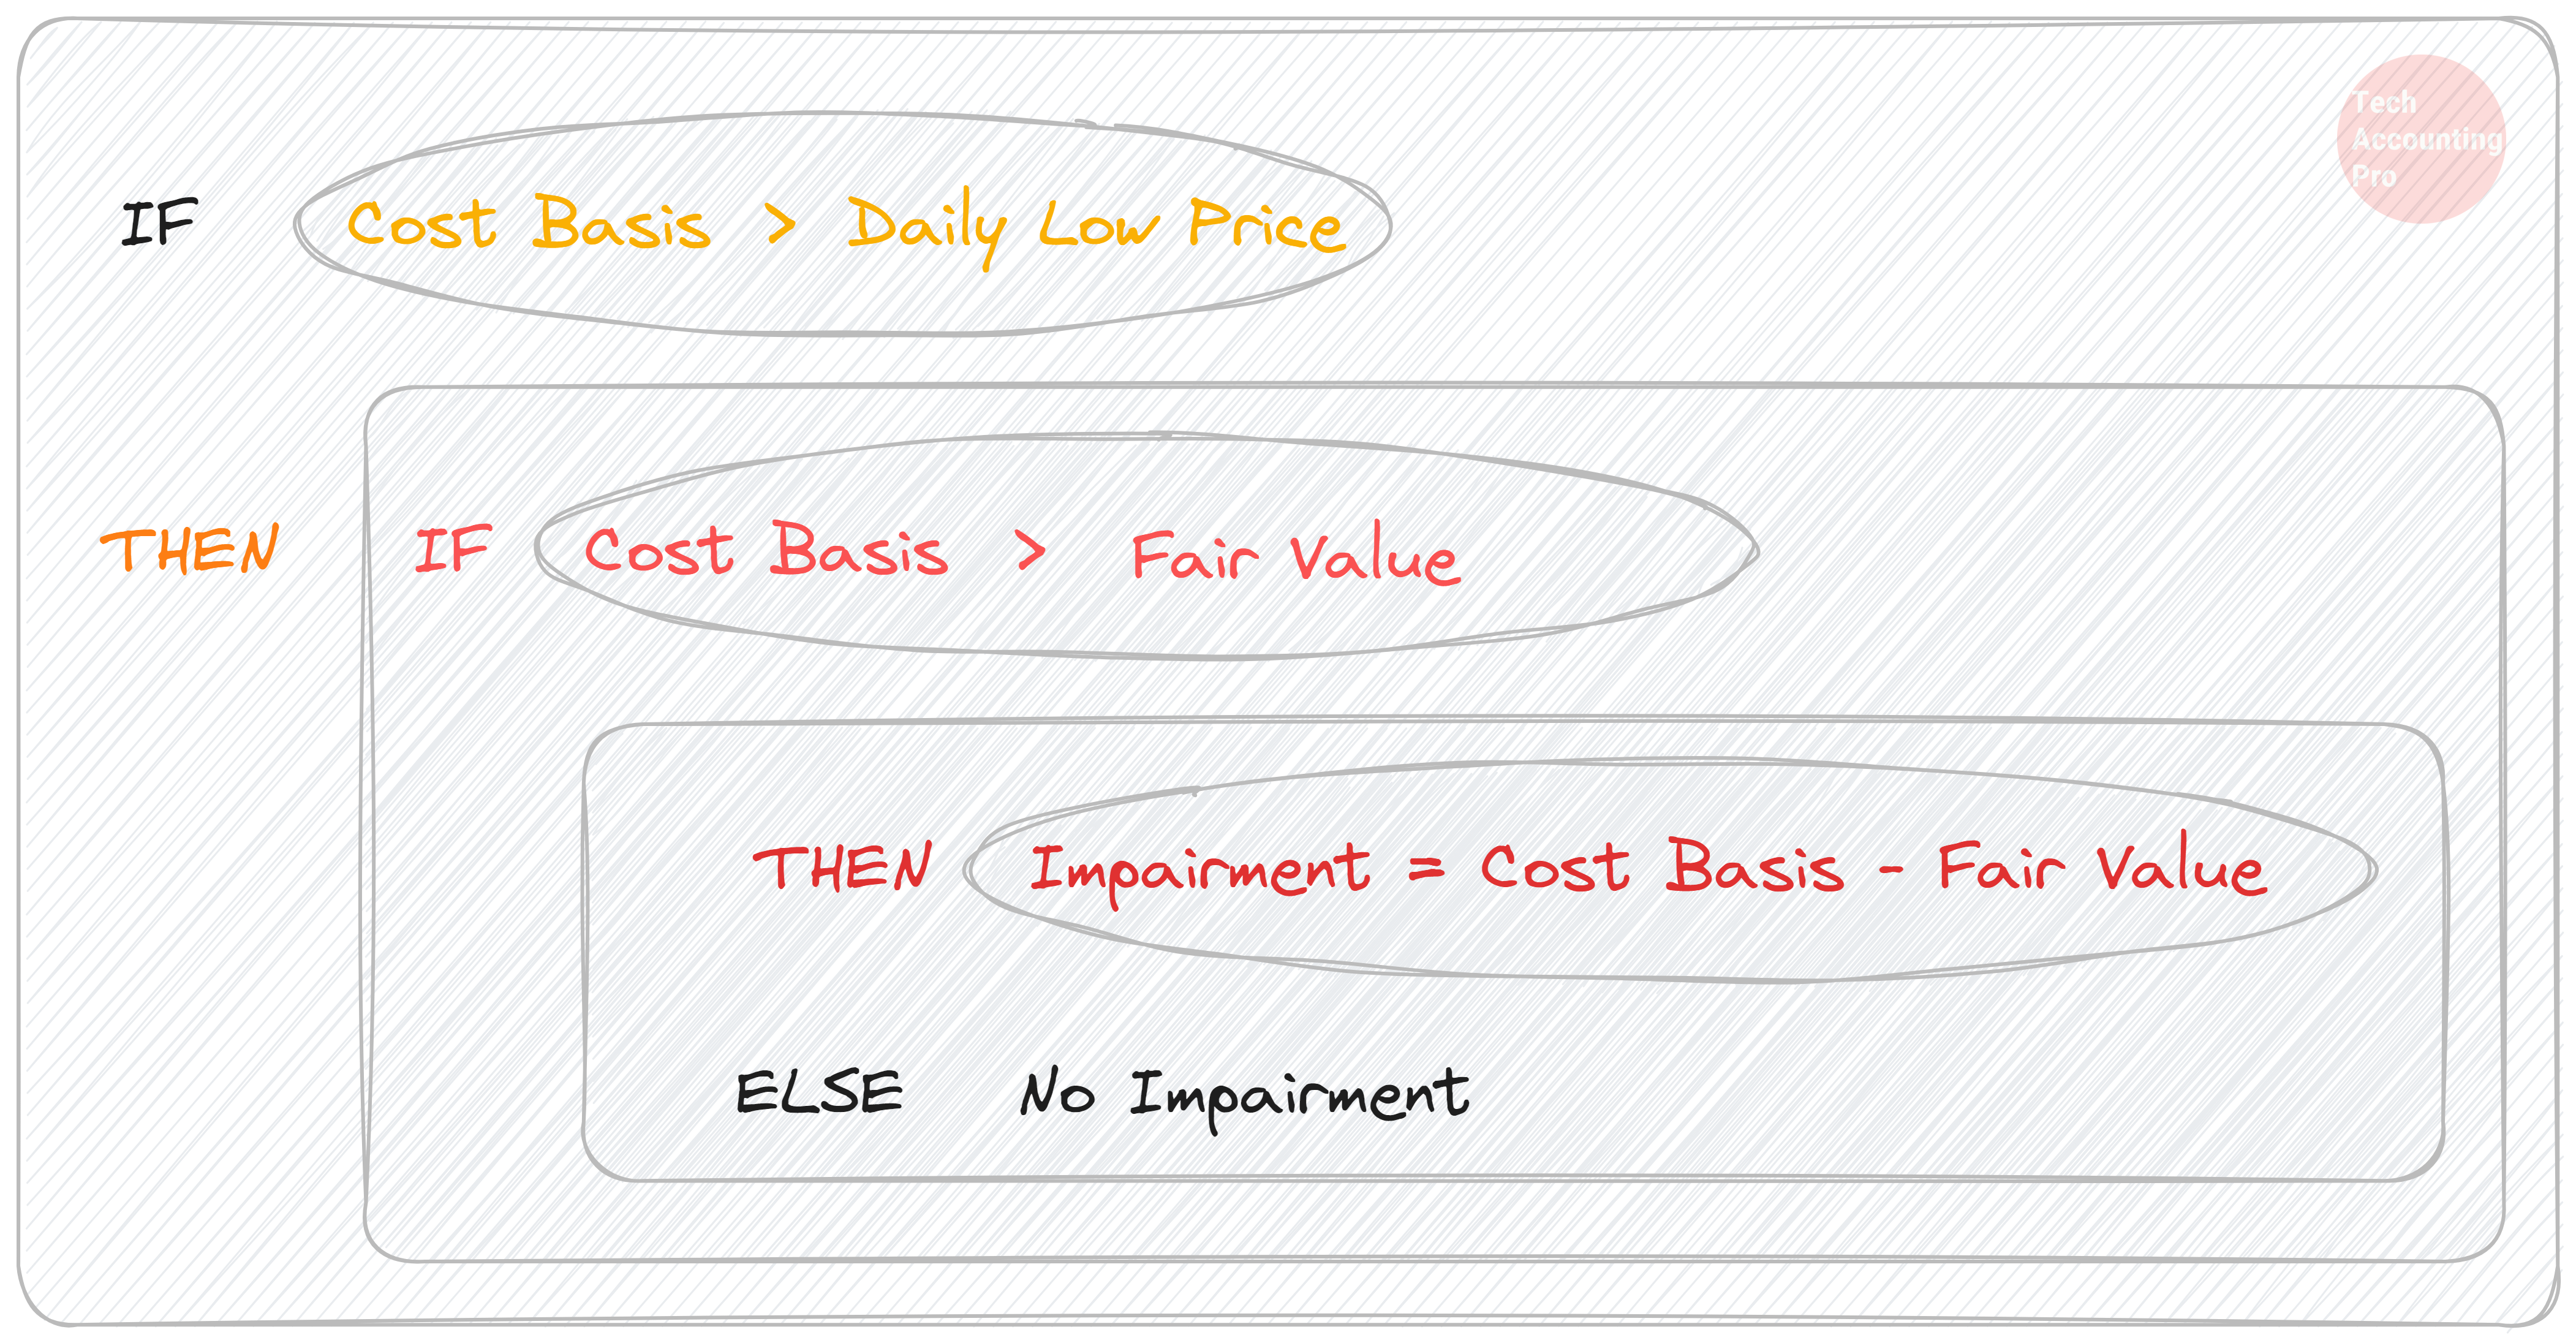
Of course, we are not even touching on the discussion around whether the calculations should be based on bid prices.
American Institute of Certified Public Accountants. (2023). Accounting for and Auditing of Digital Assets, p. 6.
Lukka Prime. (2021). Lukka Prime Methodology Whitepaper.
I suspect we will see more discussion about fair value of crypto assets once ASU 350-60 kicks in.